If you run a shop, café, salon, or trades business in Canada, card fees are one of the few costs you can cut without changing anything your customers see. Square, Moneris, and Helcim are three of the most common choices for Canadian small businesses, and they price in very different ways: Square and Moneris Flat Rate charge one blended percentage, while Helcim passes through the wholesale cost and adds a fixed markup.
This comparison is research-based. We did not process payments with any of these providers. Every rate below comes from each company's official Canadian pricing page, fee disclosure, or merchant agreement, checked in September 2026. All prices are in CAD.
The short answer
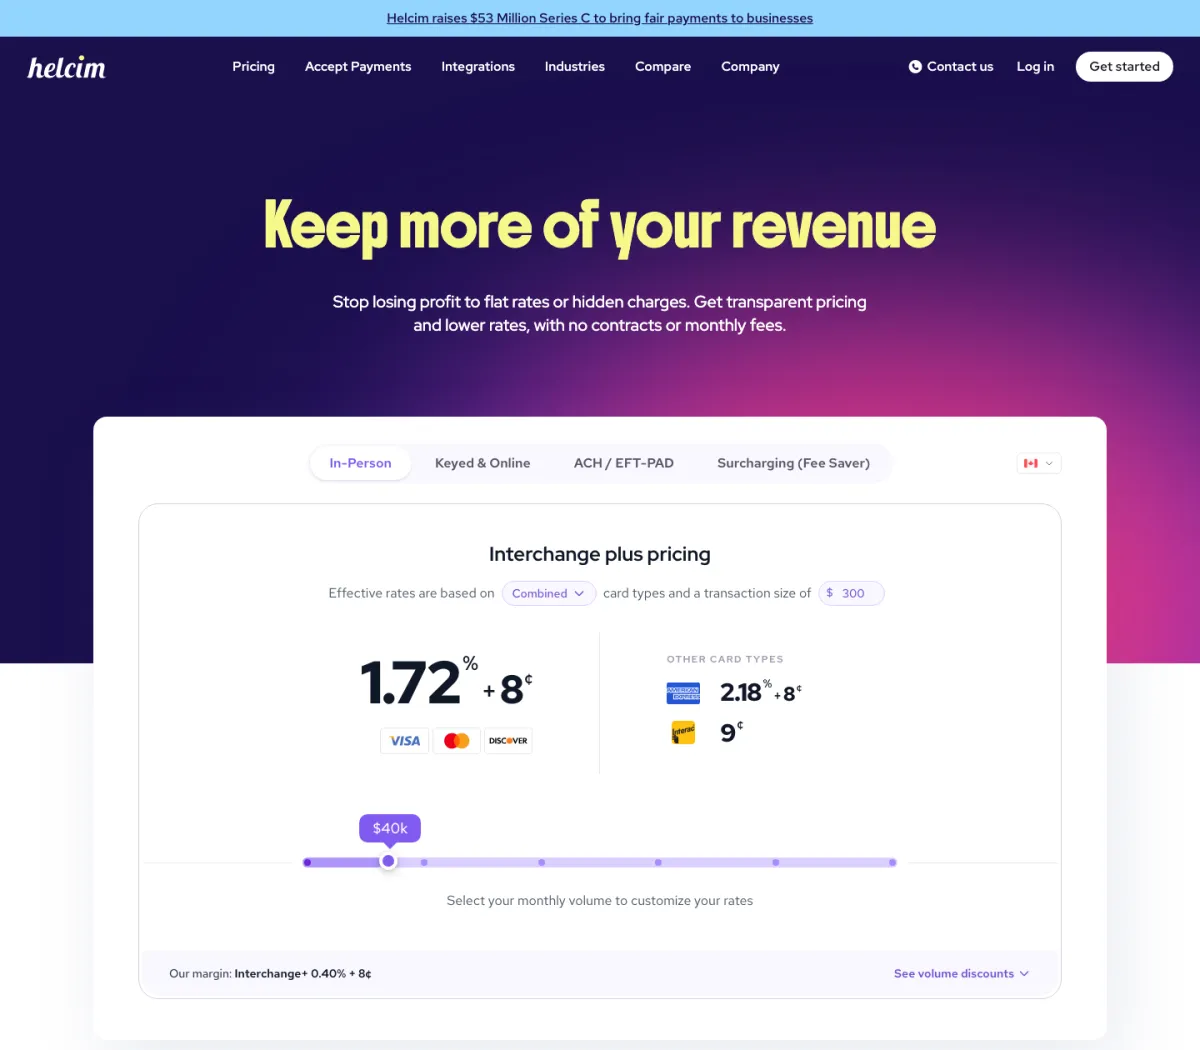
- Helcim is the lowest-cost option on published rates for most businesses that take a steady mix of credit and Interac. It charges interchange plus 0.40% + 8¢ in person on its first tier, 9¢ to 12.5¢ for Interac, no monthly fee, and no cancellation penalty.
- Square is the simplest. One flat 2.5% on in-person credit, a free POS plan, a $69 reader, and a plan you can cancel at any time. Its Interac rate is percentage-based, so it suits businesses with smaller average debit sales.
- Moneris makes the most sense if you want a processor that works with RBC and BMO and next-day deposits into those accounts. Its Flat Rate plan is published; hardware is rented, and the standard merchant agreement has a three-year term.
| Feature | Square | Moneris | Helcim |
|---|---|---|---|
| Pricing model | Flat rate | Flat Rate or interchange-plus (quote) | Interchange-plus |
| In-person credit | 2.5% | 2.65% + 10¢ | Interchange + 0.40% + 8¢ |
| Interac debit (in person) | 0.75% + 7¢ | 12¢ | 9¢ chip, 12.5¢ tap |
| Online credit | 2.8% + 30¢ | 2.85% + 30¢ | Interchange + 0.50% + 25¢ |
| Keyed-in credit | 3.3% + 15¢ | 2.85% + 30¢ | Interchange + 0.50% + 25¢ |
| Monthly account fee | $0 (Free plan) | Not published | $0 |
| Entry hardware | $69 reader | $34.95/mo Go rental | $239 card reader |
| Standard payout | 1 to 2 business days | Next day (BMO/RBC) | Next business day (conditions apply) |
| Cancellation penalty | $300 per location |
These rates, plus Stripe's and Shopify Payments', are in the processing fees table of our Canadian small business software price index, which you can download as a CSV.
How card processing fees work in Canada
Every credit card sale carries three layers of cost:
- Interchange, paid to the bank that issued your customer's card. Visa and Mastercard set these rates, and they vary by card type (a basic card costs less than a premium rewards or business card) and by how the card was accepted (in person costs less than online).
- Network assessment fees, paid to the card network itself.
- The processor's markup, which is what Square, Moneris, or Helcim keep.
A flat-rate processor like Square bundles all three into one percentage. You pay 2.5% whether the customer taps a basic card or a premium travel card. That is predictable, and because one rate covers every card, low-cost cards are charged the same rate as premium ones.
An interchange-plus processor like Helcim shows you the real interchange on each transaction and adds a fixed markup. Your total cost moves with your customers' card mix, and the markup is shown separately rather than inside a blended rate.
Why Interac costs so much less than credit
Interac debit is priced very differently from credit. Moneris and Helcim charge a flat amount per Interac transaction (12¢ and 9¢ to 12.5¢ respectively), and Stripe Terminal charges 15¢. On a $40 sale, 12¢ is 0.3%, compared with 2.5% or more for credit. That is why the Interac rate matters so much for Canadian businesses: many customers pay with debit, and a processor that charges a percentage on Interac (as Square does) narrows that gap as sales get larger.
Square pricing in Canada
Square publishes simple flat rates on its Canadian pricing page:
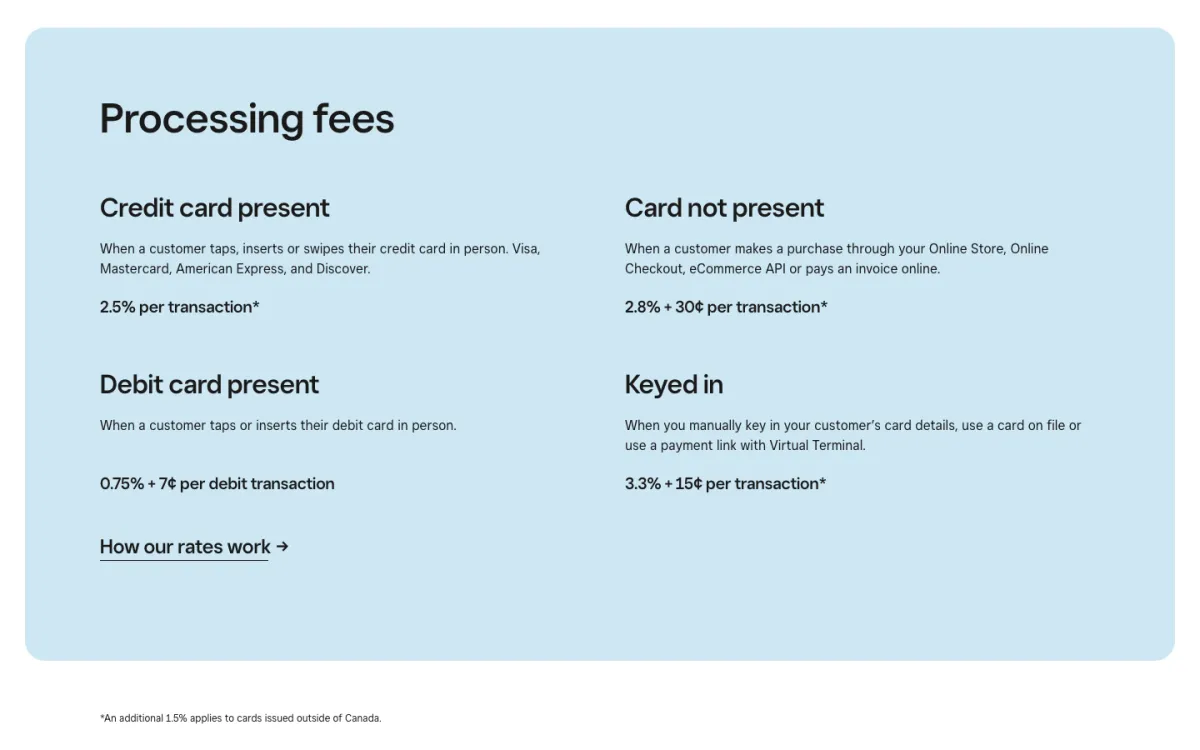
- In person (tap, chip, swipe, Tap to Pay): 2.5% per credit transaction
- Interac debit in person: 0.75% + 7¢ per transaction
- Online: 2.8% + 30¢
- Keyed-in or card on file: 3.3% + 15¢
- Cards issued outside Canada: an extra 1.5%
Square's help centre states that fees apply to the full transaction amount, including tax and tip, and that the same rate applies to every card brand.
The Free plan has no monthly fee and covers selling in person, online, over the phone, and in the field. Paid Plus plans start at $35/month plus processing fees. Square's pricing FAQ says you can upgrade, downgrade, or cancel a plan at any time.
Hardware is bought, not rented: the Square Reader is $69, Square Terminal is $399, Square Handheld is $449, Square Stand is $249, and Square Register is $999. Standard transfers to your bank take one to two business days at no charge. Instant transfers cost 1.5% of the transfer.
For Interac, Square charges 0.75% + 7¢, so a $20 debit sale costs 22¢, a $100 sale costs 82¢, and a $500 sale costs $3.82. Helcim charges 12.5¢ for any of those tapped. Square's Interac rate suits businesses with smaller debit tickets; if your customers pay mostly with debit and your tickets are large (furniture, auto repair, trades work), that difference adds up.
Square
Strengths
- One flat 2.5% on in-person credit, all card brands
- Free POS plan with no monthly fee
- $69 reader, no hardware rental
- Cancel at any time per its pricing FAQ
- Same account covers in-person, online, and invoices
Good to know
- Interac is 0.75% + 7¢, which suits smaller debit tickets
- One flat rate for every card type, including low-cost cards
- Keyed-in transactions cost 3.3% + 15¢
- Free standard payouts take 1 to 2 business days
Square
For plans, hardware, payouts, and offline limits in more depth, read our full Square review.
Moneris pricing in Canada
Moneris works with RBC and BMO (its merchant agreement is entered into on behalf of both banks), and it offers two pricing plans. Only one is fully published.
Moneris Flat Rate charges one rate regardless of card brand, and Moneris's pricing page says this includes American Express:
- Card present credit: 2.65% + 10¢
- Card present Interac debit: 12¢
- Card not present credit (online, phone): 2.85% + 30¢
- Card not present Interac: $1.00
Moneris also advertises lower bundled rates on its Moneris Go POS plans (2.45% + 10¢ on Go Retail and 2.35% + 10¢ on Go Restaurant, with Interac at 12¢), paid alongside a monthly POS software fee. See our POS system comparison for those bundles, and confirm in writing which rate your agreement uses.
Moneris Simplified Pricing is its interchange-plus (cost plus) option. You pay interchange, network assessment fees, and a Moneris transaction fee, but the transaction fee is not published. Pricing is quote-based, and you request it through a contact form.
Moneris also publishes incidental fees, including a $25 chargeback fee, a $5 Moneris Go software fee, a $5 minimum merchant discount rate, and a $2 paper statement fee. The pricing page does not say how often each one applies, so ask for that in writing.
Hardware is rented. The Moneris Go terminal lists at $34.95/month for either model. At the time of writing, Moneris is advertising a limited-time promotion of 50% off annual rental fees; that is a promo, not the regular price.
The bigger decision is the contract. Moneris's standard small business merchant agreement terms (April 2026) set a three-year initial term that automatically renews in six-month terms unless you give notice at least 45 days before the term ends. When the agreement ends, you pay a $300 deactivation fee for each location, and you must return rental equipment. Next-day deposits are available if you bank with BMO or RBC.
Moneris
Strengths
- Published Flat Rate that includes Amex
- Low 12¢ Interac rate in person
- Next-day deposits with BMO or RBC
- Interchange-plus available on request
Good to know
- Standard agreement has a three-year initial term
- $300 per-location deactivation fee on termination
- Terminal is rented at $34.95/month
- Interchange-plus pricing is quote-based rather than published
- Online Interac costs $1.00 per transaction
Moneris
For the full contract terms, POS bundles, and how to exit an agreement, read our full Moneris review.
Helcim pricing in Canada
Helcim uses interchange-plus pricing on every account and publishes its markup by monthly volume. For card-present sales, the tiers are:
- $0 to $50,000/month: interchange + 0.40% + 8¢
- $50,001 to $100,000: interchange + 0.35% + 7¢
- $100,001 to $500,000: interchange + 0.25% + 7¢
- $500,001 to $1,000,000: interchange + 0.20% + 6¢
- Over $1,000,000: interchange + 0.15% + 6¢
Card-not-present (online and keyed) starts at interchange + 0.50% + 25¢ on the first tier and drops to 0.15% + 15¢ at the top tier. The discount applies automatically as your volume grows; you do not negotiate for it.
Interac is a flat fee. Helcim's Canadian fee disclosure lists 9¢ for chip and PIN and 12.5¢ for tap on its first volume tier (its pricing page rounds the tap fee to 12¢), with lower Interac fees at higher tiers. There is no monthly account fee, no setup fee, no PCI fee, and no cancellation fee, and the disclosure states there are no penalties for termination. A lost chargeback costs $15; a won one is free.
Hardware is sold outright: the Helcim Card Reader is $239, and the Smart Terminal is $429. Optional mobile data for the terminal is $9/month. Deposits arrive the next business day at no extra charge for batches up to $25,000 closed by 7 PM MT, if your bank account accepts Interac e-Transfer deposits; otherwise allow 1 to 2 business days.
The tradeoff is predictability. Because interchange varies by card, your monthly statement will not be a single neat percentage. If your customers carry many premium rewards or business cards, your interchange will be higher than average. You still pay only the published markup on top.
Helcim
Strengths
- Interchange-plus with published markups
- Automatic volume discounts across five tiers
- Interac at 9¢ chip, 12.5¢ tap
- No monthly, setup, or cancellation fees
- Free next-business-day deposits (conditions apply)
Good to know
- Total rate varies with your customers' card mix
- Card reader is $239 upfront, against Square's $69 reader
- Statements itemize interchange, so they have more lines than a flat rate
- Online markup of 0.50% + 25¢ on the first tier
Helcim
For every volume tier, EFT payments, and surcharging rules, read our full Helcim review.
Worked example: $20,000 a month in person
Here is what each provider would charge on the same month, using only the published rates above.
Assumptions:
- $20,000 in in-person sales, all tapped or inserted
- $14,000 on domestic Visa and Mastercard credit across 350 sales ($40 average)
- $6,000 on Interac debit across 150 sales ($40 average), all tapped
- Square Free plan, Moneris Flat Rate, Helcim first volume tier
- No hardware, rental, chargeback, or incidental fees included
| Feature | Square | Moneris Flat Rate | Helcim (markup only) |
|---|---|---|---|
| Credit, percentage | 2.5% × $14,000 = $350.00 | 2.65% × $14,000 = $371.00 | 0.40% × $14,000 = $56.00 |
| Credit, per sale | None | 350 × 10¢ = $35.00 | 350 × 8¢ = $28.00 |
| Interac | 0.75% × $6,000 + 150 × 7¢ = $55.50 | 150 × 12¢ = $18.00 | 150 × 12.5¢ = $18.75 |
| Total processor charges | $405.50 | $424.00 | $102.75 plus interchange |
Helcim's total needs interchange added, and that depends on your customers' cards, so we cannot give you one number. For a sense of scale: the federal agreement with Visa and Mastercard targets an annual weighted average interchange of 0.95% for in-store consumer credit at qualifying small businesses. If your credit interchange averaged exactly 0.95%, that would add $133.00, for roughly $235.75 before network assessment fees. That 0.95% is a benchmark for illustration, not a quote, and premium or business cards cost more.
Two things stand out. First, Square and Moneris land within about $20 of each other on this mix, but Moneris would add $34.95 if you rent a Moneris Go terminal. Second, the Interac line shows the gap: Square charges $55.50 on $6,000 of debit, while Moneris and Helcim charge under $19.
If your average sale were $100 instead of $40, Square's Interac cost would rise (0.75% + 7¢ is 82¢ per sale) while Moneris and Helcim would stay flat per transaction.
Online payments and keyed-in sales
For online checkout, Square charges 2.8% + 30¢, Moneris Flat Rate charges 2.85% + 30¢, and Helcim charges interchange + 0.50% + 25¢. Online interchange is higher than in-person interchange, so Helcim's advantage narrows here, but you still avoid a blended markup.
Keyed-in sales (card numbers taken over the phone) are Square's highest rate, at 3.3% + 15¢. Moneris counts phone orders as card-not-present at 2.85% + 30¢, and Helcim uses its card-not-present tier. If you take a lot of phone payments, such as deposits for trades jobs, that difference matters.
If you sell mostly online, also look at our guide to starting an online store in Canada, since your ecommerce platform may bundle its own payment processor.
Also consider: Stripe
If you sell only online, Stripe is worth comparing. Its Canadian pricing page lists 2.9% + CA$0.30 per successful domestic card payment online, plus 0.8% for international cards, 0.5% for manually entered cards, and 2% for currency conversion. There are no setup or monthly fees on standard pricing. For in-person sales through Stripe Terminal, it lists 2.7% + CA$0.05 for most cards and CA$0.15 for Interac debit. Standard payouts are free, and instant payouts cost 1% (minimum CA$0.60).
Stripe is built for developers and online platforms more than for walk-in retail, so it fits best when your sales happen through a website, app, or subscription billing.
Your rights under the Code of Conduct
The Code of Conduct for the Payment Card Industry in Canada applies to the card networks (including Visa, Mastercard, Interac, and American Express) and the processors that work with them. The Financial Consumer Agency of Canada (FCAC) oversees it and handles merchant complaints. It was revised in 2024. Key protections for you:
- Your processor must give you 30 to 60 calendar days' notice before a fee increase or new fee.
- You can cancel your contract without penalty within 70 calendar days after a fee change takes effect.
- You can decline to renew by telling your processor at least 45 calendar days before your agreement is set to renew, and a fixed-term agreement can only renew automatically for periods of 6 months or less.
- Monthly statements must show your effective merchant discount rate, transaction counts and volumes by card type, and itemized interchange and network fees.
- You cannot be signed up for new services without your express consent.
The Moneris agreement reflects this: it lets you cancel without penalty within 70 days of a fee increase, a new fee, or an interchange reduction that is not passed on to you in full.
The small business interchange cut
The federal government announced agreements with Visa and Mastercard to lower credit card fees for small businesses, and they took effect on October 19, 2024. For qualifying businesses, in-store domestic consumer credit interchange drops to an annual weighted average of 0.95%, and online consumer credit interchange drops by 10 basis points. You qualify if your annual Visa volume is below $300,000 or your annual Mastercard volume is below $175,000. The government says more than 90% of businesses that accept credit cards will see reductions of up to 27%.
Note that this cuts interchange, not your processor's price. On an interchange-plus plan like Helcim's, a lower interchange flows straight to your bill. On a flat rate like Square's 2.5% or Moneris Flat Rate, you keep paying the published rate unless the processor lowers it. Under the revised Code, processors must tell you if a reduction will not be passed on in full, and on an agreement with no fixed term they must also tell you of your right to cancel without penalty.
Which should you pick?
Pick Helcim if you process a steady volume of in-person credit and debit, you want the lowest published cost, and you are comfortable reading a statement where the rate varies with card mix. It is also the natural home for the 2024 interchange reductions, since they pass straight through.
Pick Square if you want the simplest setup: a $69 reader, a free POS plan, one flat credit rate, and a plan you can cancel at any time. It suits new businesses, market vendors, and anyone with small average tickets where the 0.75% Interac fee stays small.
Pick Moneris if you bank with RBC or BMO and value next-day deposits into those accounts, or if you want a larger processor with interchange-plus pricing negotiated through a sales rep. Read the agreement carefully for the term and the $300 per-location deactivation fee.
If you are also choosing software to invoice clients before they pay, see our invoicing software comparison.
Our verdict
4.5For most Canadian small businesses taking steady in-person payments, Helcim has the lowest published cost: interchange plus 0.40% + 8¢, Interac from 9¢, no monthly fee, and no cancellation penalty. Square is the pick if you want one flat rate, low-cost hardware, and a free POS, especially when your Interac tickets are small. Moneris fits businesses tied to RBC or BMO that want next-day deposits and are comfortable with its standard three-year agreement and rented terminals. If you sell only online, compare Stripe's 2.9% + CA$0.30 as well.
Frequently asked questions
Which is cheapest in Canada: Square, Moneris, or Helcim?
On published rates, Helcim usually costs least because it charges interchange plus a small markup (0.40% + 8¢ in person on its first volume tier) with no monthly fee. Square and Moneris Flat Rate land close to each other for in-person credit, but Square charges more on Interac debit as your average sale grows.
How much does it cost to accept Interac debit?
Helcim charges 9¢ for chip and PIN and 12.5¢ for tap, per its Canadian fee disclosure. Moneris Flat Rate charges 12¢ in person. Square charges 0.75% + 7¢ per Interac transaction, so on a $40 sale that is 37¢.
Does Moneris have a contract?
Moneris's standard small business merchant agreement (April 2026 version) has a three-year initial term that renews automatically in six-month terms unless you give 45 days' notice, and it lists a $300 deactivation fee per location when the agreement ends. Check the specific agreement you are offered.
Can I cancel Square or Helcim at any time?
Square's pricing FAQ says you can upgrade, downgrade or cancel your plan at any time. Helcim's Canadian fee disclosure states there are no penalties for termination.
Did small business credit card fees go down in Canada?
Yes. Under agreements with Visa and Mastercard announced by the federal government, lower interchange rates for qualifying small businesses took effect on October 19, 2024. You qualify with annual Visa volume below $300,000 or Mastercard volume below $175,000, and the savings reach you directly only if your processor passes interchange through.
Contractors and service businesses that invoice large amounts have more options than a card terminal, including e-Transfer and pre-authorized debit. See our guide to how Canadian contractors should take payments.
Sources
- Square Canada: pricing (checked September 2026)
- Square Canada Support: What are Square's fees (checked September 2026)
- Square Canada: hardware shop (checked September 2026)
- Moneris: pricing (checked September 2026)
- Moneris: Moneris Go (checked September 2026)
- Moneris Merchant Agreement Terms and Conditions, April 2026 (checked September 2026)
- Helcim: pricing (checked September 2026)
- Helcim: Canadian fee disclosures (checked September 2026)
- Stripe Canada: pricing (checked September 2026)
- FCAC: Merchant rights under the Code of Conduct for the Payment Card Industry in Canada (checked September 2026)
- Department of Finance Canada: Government reduces credit card fees by 27 per cent for small business owners (checked September 2026)